After a car accident, many drivers expect their insurance company to cover the full cost of restoring the vehicle.
Then the estimate arrives.
The repair shop says one amount, while the insurance company says it will pay another. Somewhere in the paperwork, you may see terms such as betterment, depreciation, deductible, or customer responsibility.
So what are betterment charges, and why can they make an insurance payout appear lower than the actual repair cost?
Betterment generally refers to an amount an insurer may deduct when replacing a damaged part with a newer part would leave the vehicle in a better condition than it was immediately before the loss. Whether betterment applies, how it is calculated, and what parts may be subject to it depend on the insurance policy, applicable law, and circumstances of the claim.
For Philadelphia drivers, understanding the concept can make insurance conversations and collision repairs easier to navigate.
What Are Betterment Charges?
Betterment is based on the idea that an insurance claim is intended to restore a vehicle to its pre-loss condition rather than improve it beyond that condition.
For example, imagine an older vehicle has a worn component that is damaged in an accident. If the repair requires a new replacement component, the new component could potentially have a greater remaining useful life than the damaged one had before the accident.
An insurer may argue that the vehicle owner is receiving an improvement in value or useful life.
That difference may be referred to as betterment.
However, betterment is not the same thing as your deductible, and it should not automatically be assumed to apply to every repair.
Betterment vs. Your Deductible
These two terms are easy to confuse.
Deductible
Your deductible is the amount you are responsible for under the terms of your insurance policy before the insurer pays its covered portion of a claim.
Betterment
Betterment is a potential adjustment related to replacing certain damaged components with newer or improved components.
They are separate concepts.
For example, an insurance settlement could potentially involve:
- A deductible
- A betterment adjustment
- Excluded damage
- Policy limits
- Other customer responsibility
The exact treatment depends on your policy and claim.
If you’re unsure why your payout is lower than expected, ask the insurance company to explain every deduction separately.
Why Would Insurance Apply Betterment?
The basic reasoning behind betterment is preventing an insurance payment from leaving the vehicle owner in a financially improved position compared with immediately before the accident.
Consider a hypothetical example.
Suppose an older vehicle has a component with significant wear. An accident damages that component, and the appropriate repair requires installing a new replacement.
The replacement component may have substantially more useful life than the damaged component had before the accident.
An insurer may consider whether an adjustment is appropriate.
The important point is that betterment isn’t simply another name for “the repair is expensive.”
It relates to the difference between replacing something damaged with a new component and restoring the vehicle’s pre-loss condition.
What Parts Could Potentially Be Affected?
Betterment considerations can vary depending on the part and the circumstances.
Parts that experience wear and have a limited useful life can sometimes raise different questions from structural body components.
Examples could include certain:
- Tires
- Batteries
- Mechanical components
- Wear-related parts
By contrast, replacing a damaged body panel isn’t automatically the same situation as replacing a worn component.
Whether an adjustment applies depends on the policy, claim, part, vehicle, and applicable rules.
That’s why it’s important to ask the insurer to identify exactly which item has been adjusted and why.
Does Betterment Apply to Every Collision Repair?
No.
A driver shouldn’t assume that every collision repair will result in a betterment charge.
The possibility depends on the circumstances and the applicable insurance terms.
If your vehicle has damaged doors, fenders, bumpers, quarter panels, or other body components, the repair estimate may involve replacement parts without necessarily creating a betterment adjustment.
If your insurer has included a betterment deduction, ask for a written explanation of the calculation.
Why Your Insurance Payout May Be Lower Than the Repair Estimate
Betterment is only one possible reason an insurance payout may differ from a repair estimate.
Other factors can include:
Your Deductible
Your policy may require you to pay a deductible.
Different Repair Estimates
The insurer and repair shop may initially identify different repair operations or parts.
Hidden Damage
Additional damage may be discovered after the vehicle is disassembled.
Policy Limits
Coverage may be subject to applicable limits.
Exclusions
Certain damage or expenses may fall outside the policy.
Parts and Repair Methods
The insurer and repair facility may have different positions regarding parts or repair procedures.
This is why you should ask for an explanation of the entire difference rather than assuming that betterment is responsible for everything.
What Happens When a Repair Shop Finds More Damage?
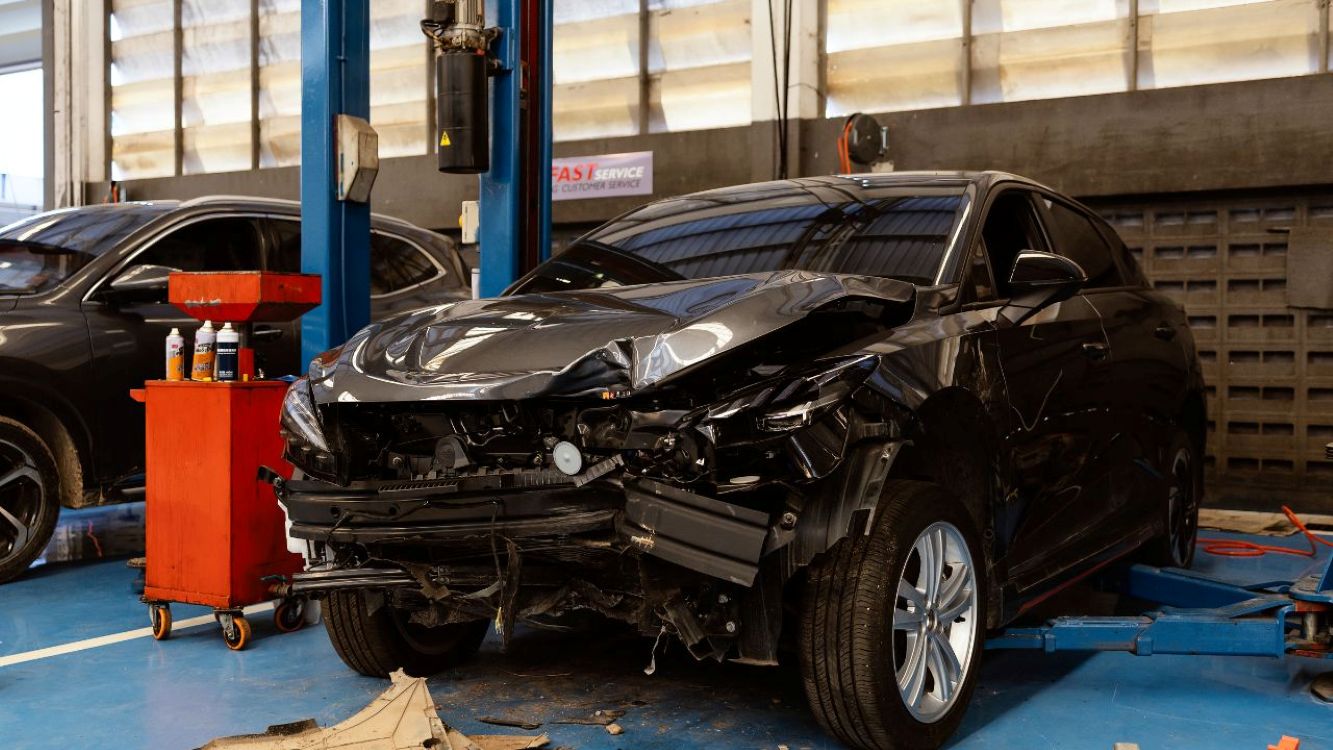
A collision can cause damage that isn’t visible during the initial inspection.
For example, a bumper may look damaged on the outside while brackets, reinforcement components, sensors, or other parts behind it are also affected.
Once the vehicle is disassembled, technicians may discover additional accident-related damage.
The repair shop can document that damage and communicate the additional repair requirements through the appropriate insurance process.
This can lead to an updated estimate or supplement.
If your vehicle needs collision repair in Philadelphia, ask the repair facility how it handles additional damage discovered during the repair process.
What Should You Do If Your Insurance Payout Falls Short?
Don’t immediately agree to pay the difference without understanding why it exists.
Start by asking the insurer for a detailed explanation.
Ask These Questions
- What amount was deducted for betterment?
- Which specific part is subject to betterment?
- How was the amount calculated?
- Is the deduction based on depreciation or another policy provision?
- What deductible applies?
- Are there other exclusions or limits affecting the payment?
- Can the insurer provide the relevant policy language?
- What amount is being paid directly toward the repair?
Having the answer to each question can help you determine what is actually creating the difference.
Review the Repair Estimate Carefully
You should also compare the insurance estimate with the repair shop’s estimate.
Look for differences in:
- Parts
- Labor
- Paint work
- Repair procedures
- Replacement components
- Additional damage
- Betterment
- Deductible
- Customer responsibility
Don’t focus only on the final total.
Two estimates can have different totals because they include different work.
Can a Repair Shop Explain Betterment?
A collision repair facility can help explain how the insurance estimate relates to the physical repairs your vehicle needs.
For example, the shop may be able to point out which components are damaged and what repair operations are necessary.
However, the insurance company determines coverage according to the applicable policy and claim circumstances.
If you have questions about whether an insurance adjustment is permitted under your policy, speak directly with your insurer and, when appropriate, a qualified insurance or legal professional.
How to Avoid Surprises Before Repairs Begin
One of the best ways to reduce confusion is to ask questions before authorizing repairs.
Request an explanation of:
- The total repair estimate
- Your deductible
- Any betterment adjustment
- Parts being used
- Potential hidden damage
- Additional repair procedures
- Your expected out-of-pocket responsibility
If something doesn’t make sense, ask for clarification.
You should understand what you’re being asked to pay before moving forward.
Choosing an Auto Body Shop After an Accident
Price is important, but it shouldn’t be the only consideration when choosing a repair facility.
Look for a shop that communicates clearly and can explain the repair estimate in understandable terms.
Important considerations include:
- Experience with collision damage
- Transparent estimates
- Clear communication
- Documentation of additional damage
- Information about parts
- Repair timeline
- Warranty information
If you need auto body repair in Philadelphia, a professional inspection can help determine the actual repair requirements before you make decisions about the claim.
Does Betterment Mean Your Insurance Company Is Refusing to Pay?
Not necessarily.
A betterment adjustment doesn’t automatically mean the insurer is denying your entire claim.
It generally means the insurer has made a specific adjustment to the amount it considers payable.
Ask for the adjustment in writing and determine exactly what part of the claim it affects.
If you disagree with the decision, you can ask the insurer to review the matter and explain the applicable policy language and calculation.
Conclusion
Understanding betterment charges explained can help Philadelphia drivers make sense of an insurance payout that doesn’t match the amount shown on a repair estimate.
Betterment is different from your deductible and is not automatically applied to every collision repair. If an insurer makes a betterment adjustment, ask which component is affected, how the amount was calculated, and what policy provision supports the deduction.
Most importantly, don’t focus only on the final payout. Compare the insurance estimate with the actual repair requirements and ask questions about every difference.
Nigro’s Auto Body can help Philadelphia vehicle owners understand the physical damage identified during a collision repair assessment and explain the repair work reflected in an estimate.
If you’ve been involved in an accident and need help understanding your vehicle’s repair needs, contact Nigro’s Auto Body for a collision repair assessment and discuss your next steps with the repair team.
Frequently Asked Questions
Betterment is a potential adjustment to an insurance claim when replacing a damaged component with a newer component could provide an improvement compared with the vehicle’s pre-loss condition. Whether it applies depends on the policy and circumstances.
No. A deductible is the amount you are responsible for under your policy. Betterment is a separate potential adjustment related to the replacement of certain damaged components.
Potentially, depending on the policy, the damaged component, the circumstances, and applicable rules. Ask the insurer to explain the specific adjustment and provide the relevant policy language.
Not automatically. Whether betterment applies depends on the circumstances and the applicable policy. A new body panel replacing an accident-damaged panel isn’t automatically subject to a betterment deduction.
Several factors can cause a difference, including your deductible, betterment, policy limits, excluded damage, differences in repair estimates, or additional repair requirements.
If you believe an adjustment is incorrect, ask the insurer for a written explanation and the policy provision supporting it. You can request that the claim be reviewed and seek professional advice if necessary.
No. Betterment is not automatically applied to every claim. Its applicability depends on the policy, type of damage, replacement component, and circumstances.
Review the estimate carefully and ask about the deductible, betterment, exclusions, limits, and any difference between the insurer’s estimate and the repair shop’s estimate. Make sure you understand the proposed payment before accepting it.